Good to Great by Jim Collins — Cliff Notes Summary
Good to Great: Why Some Companies Make the Leap... and Others Don't is a management book by Jim Collins, published on October 16, 2001, per Wikipedia. Publishers Weekly lists it as a HarperBusiness hardcover of 320 pages at $27.50 (Wikipedia names HarperCollins as publisher). Wikipedia says it sold four million copies.
The book asks how an ordinary company becomes a great one. Collins's team screened 1,435 companies and found 11 that beat the stock market by at least 3 times over 15 years after a turning point, Collins wrote in Fast Company. Its answers are Level 5 leadership, First Who (the right people before the strategy), confronting the brutal facts, the Hedgehog Concept and the Flywheel.
The catch: several of the 11 later stumbled. Fannie Mae was placed into government conservatorship in 2008, and Circuit City went bankrupt that year and was liquidated in 2009. This is a short summary in our own words, not a retelling of the book, and the sales-leader takeaways are our interpretation, not the author's advice.
About the book and the research
- AuthorJim Collins
- PublisherHarperBusiness (HarperCollins)
- PublishedOctober 16, 2001
- Length320 pages (hardcover)
- ISBN978-0-06-662099-2
Publishers Weekly, reviewing it in September 2001, describes a five-year project by a 21-person research team that read and coded 6,000 articles and produced more than 2,000 pages of interview transcripts. Collins called it a prequel to Built to Last, his earlier book with Jerry Porras. HarperCollins says the team analyzed the histories of 28 companies in all: the 11 that made the leap, 11 direct comparison companies that did not, and six that rose but did not sustain it.
The bar was high. In his Fast Company article of October 2001, Collins says the 11 averaged returns 6.9 times the market's after their leap. Examples he gives: Fannie Mae at 7.56 times, Nucor at 5.16, Wells Fargo at 3.99, Abbott Laboratories at 3.98, Kimberly-Clark at 3.42 and Kroger at 4.16.
The 11 companies and their comparisons
Wikipedia lists each good-to-great company next to the comparison company Collins paired it with, a business in a similar industry with similar opportunities that did not make the leap.
- Abbott Laboratories vs. Upjohn
- Circuit City vs. Silo
- Fannie Mae vs. Great Western Bank
- Gillette vs. Warner-Lambert
- Kimberly-Clark vs. Scott Paper
- Kroger vs. A&P
- Nucor vs. Bethlehem Steel
- Philip Morris vs. R. J. Reynolds
- Pitney Bowes vs. Addressograph
- Walgreens vs. Eckerd
- Wells Fargo vs. Bank of America
The six unsustained comparisons were Burroughs, Chrysler, Harris, Hasbro, Rubbermaid and Teledyne.
The core concepts, paraphrased
- Level 5 leadership. The leaders at the turning point mixed personal humility with fierce resolve, and their ambition was for the company rather than themselves. Collins's site says every one of the 11 transitions began with such a leader, and that the comparison companies lacked them.
- First Who, Then What. Get the right people on the bus, and the wrong people off it, before deciding where to drive it, as the books page puts it. People decisions come before strategy.
- Confront the brutal facts. Keep faith that you will prevail while facing the hardest facts of your situation. Collins calls this the Stockdale Paradox, and his site warns that a strong personality can stop bad news from reaching the leader.
- The Hedgehog Concept. A simple idea at the overlap of three circles: what you are deeply passionate about, what you can be the best in the world at, and what drives your economic engine. Collins stresses it is an understanding of what you can be best at, not a goal. The name comes from Isaiah Berlin's essay built on a Greek parable, "The fox knows many things, but the hedgehog knows one big thing."
- The discipline to stop doing. In the Fast Company article, Collins says good-to-great leaders stood out for their discipline to stop doing anything that did not fit the Hedgehog Concept. His example is Kimberly-Clark, which moved into consumer paper products such as Kleenex while Wall Street analysts derided the move.
- Technology as an accelerator. In the Fast Company article, Collins says technology is important but comes into play only after a transformation has already begun, so it does not start one.
- The Flywheel. No single program, launch or miracle moment made any company great. Collins compares it to pushing a giant, heavy flywheel turn after turn until momentum builds into a breakthrough. The opposite, in the Fast Company article, is the Doom Loop: disappointing results lead to a reaction without understanding, a new leader or program, no momentum, and more disappointing results.
Collins also lists change myths the great companies avoided, in the same article: launch-event change programs, manufactured crises, stock-option incentives, fear, buying growth through acquisitions, and revolution-style upheaval.
What happened to the 11 companies afterward
This is the book's best-known weak spot. In a Freakonomics post of July 28, 2008, economist Steven Levitt wrote that anyone who bought Fannie Mae stock around publication would have lost more than 80 percent, that Circuit City was down 80 percent or more after years of losing ground to Best Buy, and that only Nucor had dramatically beaten the market. He concluded that a portfolio of the 11 would likely have trailed the S&P 500.
- Circuit City. Filed for Chapter 11 on November 10, 2008, then announced on January 16, 2009 that it would liquidate all its stores, and more than 30,000 employees lost their jobs, per Wikipedia. The Great Recession and Best Buy are named among the causes.
- Fannie Mae. Placed into conservatorship of the Federal Housing Finance Agency on September 7, 2008, along with Freddie Mac, per Wikipedia.
- Wells Fargo. Hit by the cross-selling scandal, which became widely known in late 2016: millions of accounts were opened without customers' consent under aggressive sales goals, and regulators including the CFPB fined the bank a combined $185 million. CEO John Stumpf resigned, per Wikipedia.
- Nucor, Abbott and the rest. Levitt singled out Nucor as the clear winner and called Abbott and Wells Fargo okay as of 2008. He wrote that nine of the eleven remained more or less intact at that point.
Collins's later book How the Mighty Fall, listed on his books page, studies how great companies decline. Wikipedia notes critic John Greathouse's view that it partly blames the fallen companies for changing after the earlier books were printed.
Criticisms of the method
Wikipedia collects several. Phil Rosenzweig, author of The Halo Effect, argues that leaning on magazine articles imports halo effects (successful firms get described as well run because they are successful), that focus may be a luxury of success rather than its cause, and that the study confuses correlation with causation. Holt and Cameron call the book a generic business recipe that ignores each company's particular strategic opportunities. Levitt's broader point is that books built on past winners look backward and may not predict the future.
On the positive side, Wikipedia says several members of The Wall Street Journal's CEO Council named it the best management book they had read, and Time placed it on its list of The 25 Most Influential Business Management Books. Publishers Weekly called it worthwhile while noting that many of its ideas are simple common sense.
What sales leaders can take from it (our interpretation)
The book is about whole companies, not sales teams. These are our suggestions, not the author's.
- Hire before you plan territories. First Who applied to a sales floor: fix the bench of reps and managers before you redesign comp plans or the go-to-market strategy.
- Find your sales hedgehog. Look for the overlap of the segment your team wins most often, the deal your best reps get excited about, and the metric that actually drives profit, such as gross margin per deal rather than raw bookings. Collins says Wells Fargo chose profit per employee as its economic measure.
- Run the pipeline review on brutal facts. Make it safe for reps to report slipping deals early. A leader whose mood is the main thing reps manage will hear bad news late.
- Build a flywheel, not a launch. Steady habits such as daily prospecting, consistent call reviews and the same qualification standard compound more than a new kickoff theme every quarter.
- Learn from Wells Fargo. The cross-selling scandal shows what aggressive sales goals can do without discipline and integrity. Set targets reps can hit honestly, and audit how the number was made, not only whether it was made.
- Do not copy the 11. Several of the book's examples later failed, so borrow the principles and test them on your own team's data.
Questions people ask
Who wrote Good to Great and when was it published?
Jim Collins. Wikipedia gives October 16, 2001, and Publishers Weekly lists it as a 320-page HarperBusiness hardcover.
What are the main concepts in Good to Great?
Level 5 leadership, First Who Then What (right people first), confronting the brutal facts (the Stockdale Paradox), the Hedgehog Concept, the discipline to stop doing what does not fit it, technology that comes after change starts, and the Flywheel.
What is the Hedgehog Concept?
The overlap of three circles: what you are deeply passionate about, what you can be the best in the world at, and what drives your economic engine. Collins says it is an understanding, not a goal.
Which 11 companies are in Good to Great?
Abbott Laboratories, Circuit City, Fannie Mae, Gillette, Kimberly-Clark, Kroger, Nucor, Philip Morris, Pitney Bowes, Walgreens and Wells Fargo.
What happened to the Good to Great companies?
Circuit City filed for bankruptcy in 2008 and liquidated in 2009, Fannie Mae went into conservatorship in September 2008, and Wells Fargo was fined over its cross-selling scandal in 2016. Steven Levitt wrote in 2008 that a portfolio of the 11 likely trailed the S&P 500, with Nucor the standout.
Is Good to Great still worth reading?
Many leaders still use its ideas, and the Wall Street Journal CEO Council and Time praised it. Read it as a set of principles to test, not as proof that the companies chosen would stay great.
Sources
- Wikipedia: Good to Great · Publication date, publisher, 320 pages, ISBN, sales, the 11 companies and comparisons, praise and criticism (Levitt, Rosenzweig, Holt and Cameron, Greathouse)
- Publishers Weekly review · HarperBusiness, $27.50, 320 pages, research team and scope
- HarperCollins: Good to Great · The 28 companies analyzed
- Jim Collins, Good to Great (Fast Company, October 2001) · 1,435 companies, selection criteria, return multiples, change myths, technology, the Doom Loop, stop-doing discipline, Kimberly-Clark and Wells Fargo examples
- Jim Collins: Books · Concept list, First Who, How the Mighty Fall
- Jim Collins: Level 5 Leadership · Level 5 leadership
- Jim Collins: The Hedgehog Concept · Three circles, Isaiah Berlin parable
- Jim Collins: The Flywheel Effect · Flywheel concept
- Jim Collins: Confront the Brutal Facts · Stockdale Paradox
- Freakonomics: From Good to Great ... to Below Average (Steven Levitt, 2008) · Fannie Mae and Circuit City losses, Nucor, S&P 500 comparison
- Wikipedia: Circuit City · Chapter 11 filing, liquidation, job losses
- Wikipedia: Fannie Mae · September 7, 2008 conservatorship
- Wikipedia: Wells Fargo cross-selling scandal · 2016 scandal, $185 million fines, sales goals
- Wikimedia Commons: Jim Collins (Mangoed, CC BY 3.0) · Hero photo of the author
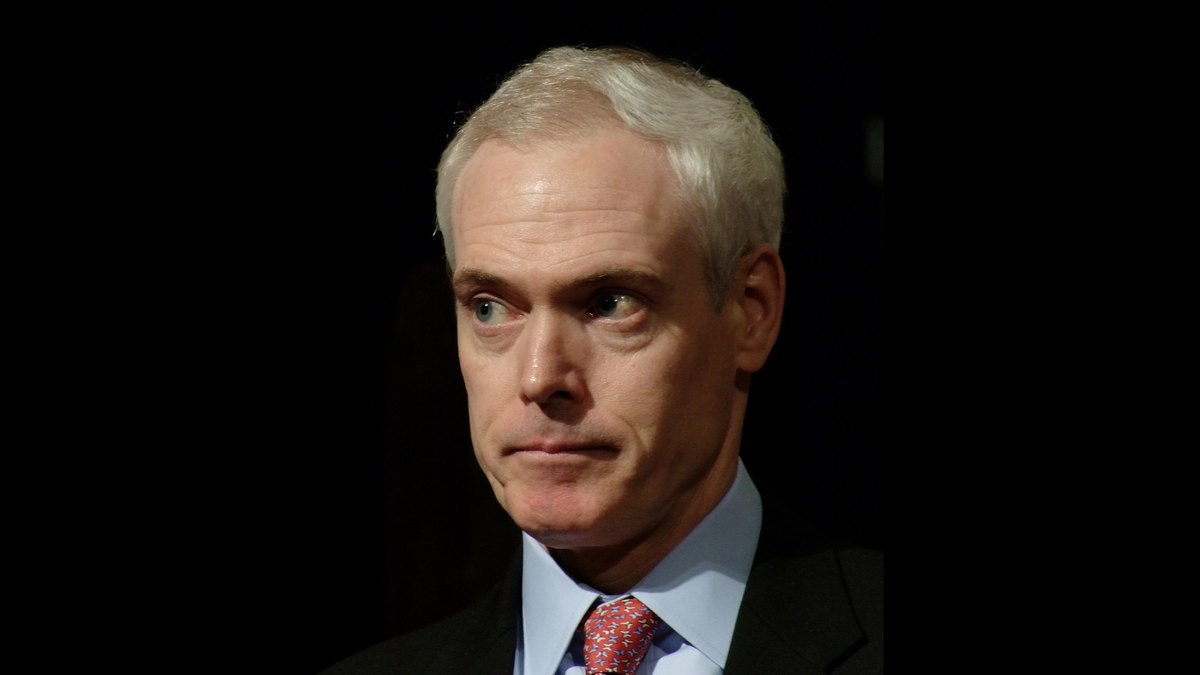
This summary is an independent explainer written in our own words and does not reproduce the book. Facts were read from the linked pages on November 3, 2026; read the book for the primary detail. The hero photo shows the author, Jim Collins, in 2009 (Mangoed, CC BY 3.0, via Wikimedia Commons).
Top photo: Mangoed / CC BY 3.0 via Wikimedia Commons